Canadian Payroll Tax Rates
What Your Employee Really Costs You
By L.Kenway BComm CPB Retired
This is the year you get all your ducks in a row! Start by starting ... and keep it simple. Consistency beats perfection.
Updated November 4, 2026 | Originally Published on Bookkeeping-Essentials.com in 2010.
WHAT'S IN THIS ARTICLE
What is Payroll Tax | What is Payroll Burden | EI Rates | What's New | EI FAQ | SE EI Voluntary Program | CPP Rates | What's New| | FAQ CPP
GO BACK TO >> Hiring Your First Employee
NEXT TOPIC >> Why You Need A Written Employment Agreement
 Why do I care about the payroll tax rates for CPP and EI? Employer payroll taxes and employee source withholdings.
Let's Talk Money
Let's talk money - specifically, what this new hire will actually cost your business. Many new employers are surprised to learn that an employee's salary is just the beginning.
You will need to budget for mandatory employer contributions to CPP (Canada Pension Plan) and EI (Employment Insurance), plus consider vacation pay and statutory holiday pay. Let's break down these costs so you can budget accurately and avoid any cash flow surprises.
What is a payroll tax?
In general, payroll taxes refers to both employee source deductions and employer contributions.
Small business owners are required to withhold and remit payroll deductions (also referred to as source deductions) to the Canada Revenue Agency (CRA) based on CPP and EI tax rates announced annually by the Canadian Government.
Employers must contribute and remit their portion of CPP and EI payroll taxes at the same time.
What is the difference between a payroll tax and an income tax withholding?
To answer that question, we need to refine the definition of payroll taxes. The 4 source deductions employers must withhold are:
- CPP contributions - this is a payroll tax on the business because the employer must contribute 1.4x the employee contribution deducted from their paycheque.
- EI premiums - this is also a payroll tax on the business because the employer must match the employee's paycheque deduction.
- Federal tax income tax - a required withholding of income tax (WIT) from the employee's paycheque.
- Provincial / territorial tax - a required withholding of income tax (WIT) from the employee's paycheque.
As income tax withholdings are paid by the employee on their earnings, they are not considered an employer payroll tax but they are a source deduction. Employer payroll taxes refer specifically to the CPP & EI amounts paid by the employer.
MORE >> Steps new employers must take before they can remit their withholdings and contributions.
Your current EI and CPP rates are found below. There is no need to get uptight about what to do with these payroll tax rates (unless you are doing your payroll manually) as your payroll software as a service (SaaS) subscription handles the calculations for you. You just need to be aware that they exist. They can be used to forecast future payroll expenses or proof program calculations.
What Is The True Cost of Your Employee?
Let's look beyond the salary and talk about what your employee really costs you. Many new employers focus only on the hourly wage or salary when budgeting for a new hire. But surprise! There's more - quite a bit more.
Salary or Hourly Wage
This is your starting point - what you've agreed to pay your employee. Whether it's $20 per hour or $40,000 per year, this is just the foundation of your total payroll costs. See what else you need to budget for.
Mandatory Employer Costs (Overview)
On top of the base pay, you're required to contribute:
- Canada Pension Plan (CPP) - You match your employee's contributions
- Employment Insurance (EI) - You pay 1.4 times your employee's contributions
- Vacation pay - Minimum 4% of gross earnings (increases with years of service)
- Statutory holiday pay - Typically adds about 4% to your payroll costs
- Workers' Compensation (varies by province and industry)
Let's look at two examples to give you a better feel for how this affects you. For this exercise, I am going to assume this is an Alberta retail business, which falls under Industry Code 66900 (Clothing/Shoe Stores), with a 2025 industry rate of $0.60 per $100 of insurable earnings.
Example #1: Real Cost of a $20/hour Employee
Let's crunch the numbers for a full-time employee in 2025:
- $20/hour × 40 hours = $800/week base pay
- + CPP (employer portion 5.95%): ~$48
- + EI (employer portion 2.3%): ~$19
- + Vacation pay (4%): $32
- + Stat holiday provision (4%): $32
- + WCB ($0.60 per $100): ~$4.80
- Weekly total: ~$936
That $20/hour employee actually costs you closer to $23.40/hour in 2025! This additional cost is oftened referred to as the payroll burden.
Example #2: Real Cost of a Salaried Employee at $40,000/year
Let's break this down to show your true annual costs in 2025:
- Base salary: $40,000
- + CPP (employer portion 5.95%): ~$2,171
[Calculation: ($40,000 - $3,500) × 5.95%] - + EI (employer portion 2.3%): ~$920
[Calculation: $40,000 × 2.3%] - + Vacation pay (4%): $1,600
- + Stat holiday pay (already included in salary)
- + WCB ($0.60 per $100): ~$240
- Annual total: ~$44,931
That $40,000 salary actually costs your business about $44,931 in 2025, or roughly $3,744 per month not $3,333 per month!
🦆Duck Tip: Notice that statutory holiday pay isn't an extra cost for salaried employees? That's because their annual salary already includes paid holidays. However, you still need to budget for someone to cover their work or accept reduced productivity during holidays. This is different from hourly employees where stat holidays are an additional cost.
🦆Quack Fact: Annual Cost Increases to Expect
Here's your heads-up for future planning:
- CPP rates generally rise every year due to inflation
- EI rates change yearly, again due to inflation
- Minimum wage requirements will affect vacation and holiday pay
- Workers' Compensation rates are typically adjusted annually
- Long-term employees earn more vacation pay (cost increases)
🦆Duck Tip: When budgeting, always add at least 15-20% to your base wage rate to estimate your true payroll costs. Better to overestimate than be caught short!
Current Year Payroll Tax Rates
Employment Insurance (EI) Notes
 EI provides temporary income support to unemployed workers
- Employers contribute 1.4 times the employee rates.
- Self-employed sole proprietors do NOT make EI contributions unless they have opted into the voluntary program. If they have joined, they pay the same rates as employees.
- EI premiums start to be deducted from the first dollar earned up to the yearly maximum.
- There are no age exemptions for deducting them.
- Employees might not be insurable if they are related to their employer, who is either a self-employed individual or a private corporation. If the business has negotiated a similar contract with an arm's length relationship, then their earnings are insurable.
- The EI clawback threshold is 1.25 x the maximum insurable earnings. That is $88,500 for 2027 versus $86,125 in 2026.
Breaking News
The 2026 Spring Economic Update (April 29, 2026) proposed to amend the Employment Insurance Act to extend a temporary measure to October 28, 2028. The measure provides up to five additional weeks of EI regular benefits to seasonal claimants in 13 regions.
It received Royal Assent in Bill C-30 in June 2026. The Bill extended the temporary seasonal support to October 7, 2028. Eligible seasonal claimants in targeted regions will continue to receive up to five additional weeks of regular benefits (maximum 45 weeks total).
It also amended the Employment Insurance Act to allow these regional boundaries to be officially managed and established by regulation. Prior to this, they were hardcoded into the text of the law itself as Schedule VI of the Act. This amendment aligns the seasonal worker regions with a smoother regulatory approach.
June 18, 2026
2027 Employment Insurance Rates
| EI Rates |
Employee Contribution Rate |
Employer Contribution Rate See Note 1 |
Maximum Insurable Earnings |
Maximum Contribution |
Self Employed Voluntary Contribution Rate See Note 2 |
Self Employed Minimum Annual Earnings Required |
|---|---|---|---|---|---|---|
| 2027 | 1.64% | 2.296% | $70,800 | $1,161.12 | 1.63% | $9,515 |
| 2026 | 1.63% | 2.282% | $68,900 | $1,123.07 | 1.63% | $9,254 |
| 2025 | 1.64% | 2.296% | $65,700 | $1,077.48 | 1.64% | $8,826 |
| 2024 | 1.66% | 2.324% | $63,200 | $1,049.12 | 1.66% | $8,492 |
| 2023 | 1.63% | 2.282% | $61,500 | $1,002.45 | 1.63% | $8,255 |
| 2022 | 1.58% | 2.212% | $60,300 | $952.54 | 1.58% | $8,092/$5,289 |
| 2021 | 1.58% | 2.212% | $56,300 | $889.54 | 1.58% | $7,555/$5,000 |
| 2020 | 1.58% | 2.212% | $54,200 | $856.36 | 1.58% | $7,279 |
| 2019 | 1.62% | 2.268% | $53,100 | $860.22 | 1.62% | $7,121 |
| 2018 | 1.66% | 2.324% | $51,700 | $858.22 | 1.66% | $6,947 |
| 2017 | 1.63% | 2.282% | $51,300 | $836.19 | 1.63% | $6,888 |
| 2016 | 1.88% 1.60% w credit | 2.632% 2.24% w credit | $50,800 | $955.04 $812.80 | 1.88% | $6,820 |
| 2015 | 1.88% 1.60% w credit | 2.632% 2.24% w credit | $49,500 | $930.60 $792.00 | 1.88% | $6,645 |
| 2014 | 1.88% | 2.632% | $48,600 | $913.68 | 1.88% | $6,515 |
| 2013 | 1.88% | 2.632% | $47,400 | $891.12 | 1.88% | $6,342 |
| 2012 | 1.83% | 2.562% | $45,900 | $839.97 | 1.83% | $6,222 |
| 2011 | 1.78% | 2.492% | $44,200 | $786.76 | 1.78% | $6,000 |
 FAQ about EI
FAQ About Canadian Employment Insurance
Following are some questions asked about employment insurance.
- When are EI rates released?
- Can you get EI if you are self-employed?
- Background: Who Sets The EI Rates?
Continue reading for the answers to these questions.
Self Employed Voluntary ProgramWhen are EI rates released?
When are EI rates released?
The Canada Employment Insurance Commission announces EI payroll tax rates (premiums) in September each year of the upcoming year.
Can you get EI if you are self-employed?
Can you get EI if you are self-employed?
Yes. The federal government first introduced Employment Insurance (EI) measures for self-employed persons in January 2010. Under this voluntary program, self-employed individuals (and corporate owners controlling more than 40% of voting shares) can enter into an agreement through Service Canada to become eligible for EI special benefits.
Important Caveats & Rules:
- Special Benefits Only: This program only covers special benefits (maternity, parental, sickness, compassionate care, and family caregiver benefits). It does not cover regular EI benefits if your business experiences a downturn or closes.
- The Point of No Return: You can opt out of the program at any time unless you have collected benefits. Once you receive even a single EI payment under this program, you can never opt out as long as you remain self-employed. Take your time making this decision.
- Exclusions: Certain independent workers (such as taxi drivers, hairdressers, and fishers covered by the EI Fishing Regulations) are already covered under regular EI rules and are not eligible for this specific voluntary program.
How much does it cost?
You pay the exact same premium rate as salaried employees, calculated on your annual tax return (via Schedule 13). Because you are self-employed, you do not have to pay the employer portion (which is normally 1.4 times the employee rate). Premiums are capped at a Maximum Insurable Earnings (MIE) threshold that changes annually.
When are rates released?
The Canada Employment Insurance Commission (CEIC) announces the upcoming year's EI payroll tax rates and maximums in September of each year.
Qualifications & Thresholds:
To qualify for a claim, you must have been registered in the program for at least 12 months. You must also meet a minimum net self-employed earnings threshold during the calendar year before your claim. This minimum earnings threshold is adjusted annually based on wage growth.
How to Apply:
Do not look for old paper forms or manual indexes. The quickest way to register is online:
- Log into your official My Service Canada Account (MSCA).
- Navigate to the Employment Insurance section.
- Select the option to opt into the EI program for self-employed people OR View my agreement status.
For the exact, up-to-date figures for the current tax year. Also refer to CRA's website pages CRA EI Premium Rates and Service Canada Self-Employed Eligibility.
Background: Who Sets The EI Rates?
Background: Who Sets The EI Rates?
The Shift to the Canada Employment Insurance Commission (CEIC)
To understand who governs your premiums, it helps to look at how rate-setting has evolved. In June 2008, the federal government established an independent crown corporation called the Canada Employment Insurance Finance Board (CEIFB) to manage the EI account and set rates.
However, in September 2013, the government permanently suspended the CEIFB to streamline operations. Since 2017, the Canada Employment Insurance Commission (the Commission) has been solely responsible for reviewing financial forecasts and setting the official premium rates every autumn.
The Commission has four members, and three of them vote. They represent workers, employers and the federal government.
Canada Pension Plan (CPP) Notes
Abbreviations EE = Employee | ER = Employer | SE = Self-Employed
YMPE = Year's Maximum Pensionable Earnings
YAMPE = Year's Additional Maximum Pensionable Earnings
 CPP provides employee retirement pension savings for the future
- CPP payroll tax rates from employers and employees will decrease to 5.75% in 2027. The rate was 5.95% from 2023 to 2026. The rate was capped at 4.95% for 2013 to 2018.
The rates began changing in 2019 due to the CPP Enhancement, which took effect on January 1, 2019. The employee and employer rate rose gradually over five years from 4.95% in 2018 to 5.95% in 2023. That extra 1% was the first part of the enhancement. It is sometimes called a top-up. A second earnings ceiling and the CPP2 rate followed in 2024 and 2025.
Prior to 2019, CPP retirement income replaced one quarter of your average work earnings. The 1% top-up raised how much of your earnings CPP replaces. The result is that CPP retirement income is now one third of your average work earnings. - First $3,500 of earnings continue to be exempt. However, thresholds and maximum contributions increase each year as average weekly salaries increase.
- Contributors cannot contribute on earnings above the ceilings. CPP1 contributions stop at the YMPE (Year’s Maximum Pensionable Earnings). CPP2 contributions stop at the YAMPE (Year’s Additional Maximum Pensionable Earnings).
Starting in 2024, a higher, second earnings ceiling was implemented and used to determine second additional CPP contributions (CPP2). As a result, pensionable earnings between YMPE and YAMPE are subject to additional contributions (CPP2). - Employers will continue to contribute 1.0 times the employee rates. This means the maximum self-employed contribution is double ($4,637.00 total employee maximum for 2027 x 2 = $9,274.00 or $772.83 per month). A good practice for the self-employed is to set aside monies monthly or make quarterly installments to pay your income tax and CPP that will become due in April each year.
- CRA's November 1, 2024 news release stated, "In 2024, a second earnings ceiling was introduced, the Year’s Additional Maximum Pensionable Earnings (YAMPE). The YAMPE is used to determine second additional Canada Pension Plan contributions (CPP2). In 2024, the YAMPE is approximately 7% above the Year’s Maximum Pensionable Earnings (YMPE). In 2025 and every year after, the YAMPE will be approximately 14% above the YMPE."
CRA employee and employer CPP2 contribution rates for 2026 and 2027 will be 4.00%, and the maximum contribution will be $416 and $428 respectively; the self-employed CPP2 contribution rate will be 8.00%, and the maximum self-employed contribution will be $832 and $856 respectively.
CPP2 is calculated as follows: (YAMPE - YMPE) x contribution rate %. For example, for 2027, the calculation is ($87,400 - $76,700) x 4% (for employees) or 8% (for self-employed). - Employees aged 18 to 69 must contribute to CPP. From 65 to 69, contributions are voluntary only for an employee who is receiving a CPP retirement pension. That employee can stop by submitting form CPT30, Election to Stop Contributing to CPP. An employee who is not receiving a pension must keep contributing. This includes someone who chose to delay their pension until age 70. Contributions end at 70 for everyone.
- Following a 2025 system update, the Canada Revenue Agency discontinued its annual news release for Canada Pension Plan (CPP) rates. Instead, updates are published quietly, leaving the public to independently gather the necessary information. Furthermore, the CRA has been slow to update its "CPP contribution rates, maximums and exemptions" webpage under this new process.
For example, the 2027 rates cited below had to be calculated manually by combining the new contribution structures passed in Bill C-30 this past June, alongside the 2027 YMPE and YAMPE limits released quietly by the CRA at the end of October.
Resource: November 1, 2024 Canada Revenue Agency announces maximum pensionable earnings and contributions for 2025
Breaking News
Effective January 1, 2027, the combined base CPP contribution rate for employees (EE) and employers (ER) will decrease from 9.9% to 9.5%. Originally announced in the Spring Economic Update on April 29, 2026, this change required legislative amendments to the Canada Pension Plan. The necessary legislation (Bill C-30) successfully received Royal Assent and passed into law on June 18, 2026.
Here is how the combined rate becomes the rate each side pays:
2026: 9.9% / 2 = 4.95% base rate + 1% enhancement (top-up) = 5.95% each for EE and ER
2027: 9.5% / 2 = 4.75% base rate + 1% enhancement (top-up) = 5.75% each for EE and ER
2027 Canada Pension Plan Rates
Table 1: Employer CPP Information
| CPP Rates |
EE/ER Contribution Rate See Note 1 |
Basic Exemptions See Note 2 |
Maximum Pensionable Earnings (YMPE) See Note 3 |
Maximum Contribution CPP1 |
Maximum Monthly Contribution CPP1 |
YAMPE See Note 5 |
EE/ER CPP2 Rate |
Maximum Contribution CPP2 See Note 5 |
TOTAL Maximum Contributions CPP1 + CPP2 |
|---|---|---|---|---|---|---|---|---|---|
| 2027 | 5.75% | $3,500 | $76,700 | $4,209.00 | $350.75 | $87,400 | 4% | $428 | $4,637.00 |
| 2026 | 5.95% | $3,500 | $74,600 | $4,230.45 | $352.54 | $85,000 | 4% | $416 | $4,646.45 |
| 2025 | 5.95% | $3,500 | $71,300 | $4,034.10 | $336.18 | $81,200 | 4% | $396 | $4,430.10 |
| 2024 | 5.95% | $3,500 | $68,500 | $3,867.50 | $322.29 | $73,200 | 4% | $188 | $4,055.50 |
| 2023 | 5.95% | $3,500 | $66,600 | $3,754.45 | $312.87 | ||||
| 2022 | 5.70% | $3,500 | $64,900 | $3,499.80 | $291.65 | ||||
| 2021 | 5.45% | $3,500 | $61,600 | $3,166.45 | $263.87 | ||||
| 2020 | 5.25% | $3,500 | $58,700 | $2,898.00 | $241.50 | ||||
| 2019 | 5.10% | $3,500 | $57,400 | $2,748.90 | $229.08 | ||||
| 2018 | 4.95% | $3,500 | $55,900 | $2,593.80 | $216.15 | ||||
Table 2: Self-Employed CPP Information
| CPP Rates |
SE Contribution Rate See Note 1 |
Basic Exemptions See Note 2 |
Maximum Pensionable Earnings (YMPE) See Note 3 |
Maximum Contribution CPP1 |
Maximum Monthly Contribution CPP1 |
YAMPE See Note 5 |
SE CPP2 Rate |
Maximum Contribution CPP2 See Note 5 |
TOTAL Maximum Contributions CPP1 + CPP2 |
|---|---|---|---|---|---|---|---|---|---|
| 2027 | 11.5% | $3,500 | $76,700 | $8,418.00 | $701.50 | $87,400 | 8% | $856 | $9,274.00 |
| 2026 | 11.9% | $3,500 | $74,600 | $8,460.90 | $705.08 | $85,000 | 8% | $832 | $9,292.90 |
| 2025 | 11.9% | $3,500 | $71,300 | $8,068.20 | $672.35 | $81,200 | 8% | $792 | $8,860.20 |
| 2024 | 11.9% | $3,500 | $68,500 | $7,735.00 | $644.58 | $73,200 | 8% | $376 | $8,111.00 |
| 2023 | 11.9% | $3,500 | $66,600 | $7,508.90 | $625.74 | ||||
| 2022 | 11.4% | $3,500 | $64,900 | $6,999.60 | $583.30 | ||||
| 2021 | 10.9% | $3,500 | $61,600 | $6,332.90 | $527.74 | ||||
| 2020 | 10.5% | $3,500 | $58,700 | $5,796.00 | $483.00 | ||||
| 2019 | 10.2% | $3,500 | $57,400 | $5,497.80 | $458.12 | ||||
| 2018 | 9.9% | $3,500 | $55,900 | $5,187.60 | $432.30 | ||||
Self-employed CPP contributions are calculated on Schedule 8 of your T1 tax and benefits return. See Note 4 above for more details.
Who does what in the Canada Pension Plan?
The Canada Pension Plan is the pension program itself. Four federal organizations each play a part in running it. The CRA collects contributions. Service Canada pays benefits. The CPPIB invests the extra funds. The Chief Actuary forecasts whether the plan is sustainable. The arrows in the graphic show how money and information move. They do not show who reports to whom.
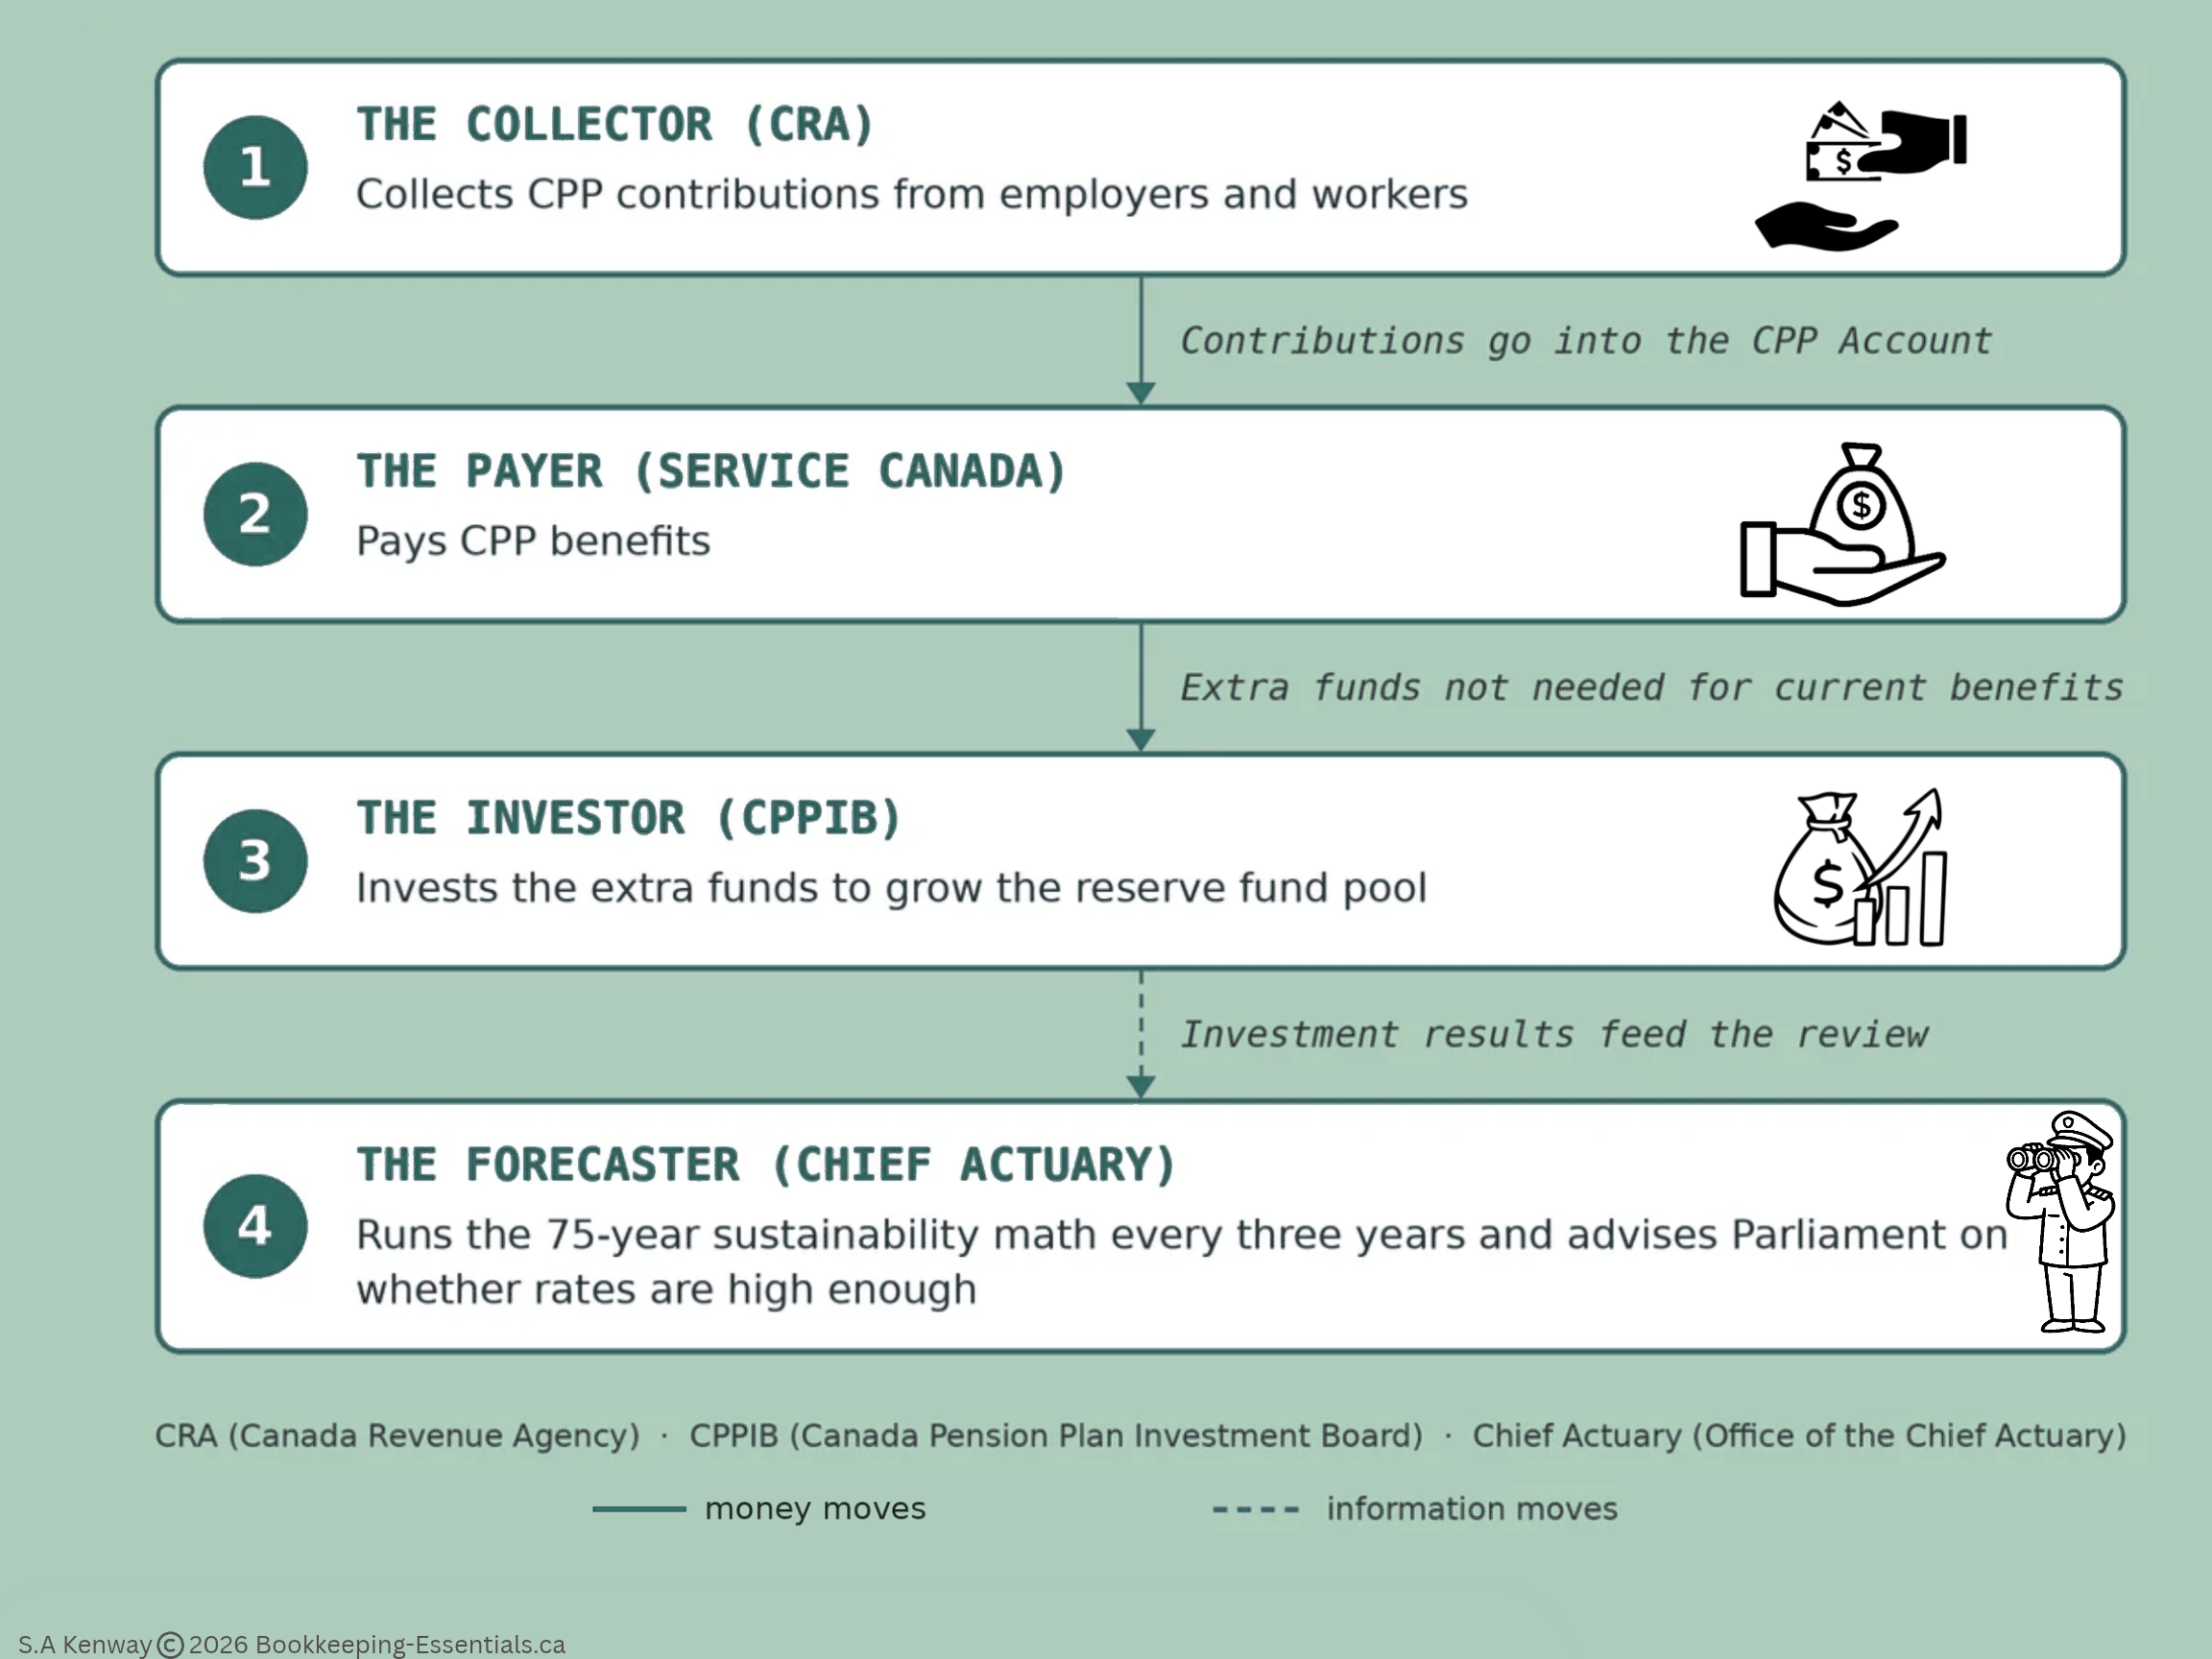 How the Canada Pension Plan program worksFAQ about CPP
FAQ about Canada Pension Plan
Here are some questions people ask about the Canada Pension Plan.
- When are CPP rates released?
- Who is excluded from paying CPP contributions and EI premiums?
- Is CPP sustainable for future generations? YES.
- Background: Who Invests the CPP contributions?
Continue reading for the answers to these questions.
CPP & EI ExclusionsWhen are CPP rates released? Who releases the CPP rates?
When are CPP rates released? Who releases the CPP rates?
The Canada Revenue Agency (CRA) quietly releases CPP payroll tax rates in late October / early November each year for the upcoming year.
The CRA is solely responsible for tax administration. It does not decide what the CPP rates should be, nor does it forecast fund performance. When Parliament passes a law changing the rate (such as lowering the base rate to 9.5% via Bill C-30), the CRA's only job is to update its tax tables, enforce payroll deductions, and collect the money from employers and workers.
Who Is Excluded From Paying CPP Contributions And EI Premiums?
Who Is Excluded From Paying CPP Contributions And EI Premiums?
As a small owner manager, the employer portion of CPP and EI is often referred to as a payroll burden. These payroll taxes hit your payroll and your business cash flow.
The question you need to ask is ... when is it legally mandatory to deduct and remit CPP contributions and EI premiums for your employees? You don’t pay them to the employees. You deduct them and send them to the CRA.
- CPP is a mandatory deduction for employees from age 18 up to 65. Between 65 and 70, there are two cases.
(1) If the employee is not receiving a CPP retirement pension, contributions are still mandatory. This includes an employee who has chosen to delay their CPP pension to age 70 for a larger monthly payment. They cannot opt out of contributing.
(2) If the employee is receiving a CPP retirement pension, contributions become voluntary. That employee can choose to stop by completing CRA Form CPT30.
Contributions end entirely at age 70 for everyone. - EI generally applies to everyone in insurable employment, provided they earn insurable income. There are no age restrictions.
🦆 Owner-Manager Caveat
If you employ family members, or if you pay yourself via salary as a corporate owner-manager controlling more than 40% of the corporation’s voting shares, those earnings are exempt from EI premiums. CPP contributions still apply.
Otherwise, everyone who is employed must contribute to EI. Employees with earnings under $2,000 receive a 100% refund when they file their tax return. The moment an employee earns even $2,001, they no longer qualify for an insurable earnings refund. From that point forward, they only get a refund if their total premiums went over the annual maximum, usually because they worked more than one job.
These are general rules. There are many exceptions. So let’s answer that question by looking at when the employer does not have to pay CPP and EI.
Some income is exempt from paying the payroll tax rates for CPP contributions and EI premiums. Check out these CRA resources to make your determination:
(1) Special payments chart - helps you determine whether or not to deduct CPP contributions, EI premiums, and income tax on the special payments you make to your employees or recipients.
(2) Benefits and allowances topical search - explains difference between a benefit, an allowance, or a reimbursement
(3) CPP/EI Explained - discusses various interpretive rulings including tips/gratuities controlled by the employer.
Is CPP Sustainable For Future Generations? Short answer is YES.
Is CPP Sustainable For Future Generations? Short answer is YES.
The independent forecasting and sustainability advice comes from the Chief Actuary, an independent watchdog housed within the Office of the Superintendent of Financial Institutions (OSFI).
Every three years, the Chief Actuary reviews the plan's financial health. The Actuary takes the CPPIB’s investment data, mixes it with Canadian demographic data (birth rates, immigration, aging population), and builds the 75-year forecasting models. The Chief Actuary then advises Parliament on whether the current payroll tax rates are high enough to keep the pension safe for future generations.
The most recent triennial report was released in December 2025. It confirmed that the CPP is financially sustainable for at least 75 years. A special report followed in June 2026 because of Bill C-30. This was an exception. The next triennial report is expected in 2028.
The Chief Actuary’s latest projections are currently based on the assumption that the base CPP account will earn an average annual real rate of return of 4.05% above the rate of Canadian consumer price inflation, after all expenses, over the 75-year projection starting in year 2025. The projections also assume that the additional CPP account, which targets a lower level of risk, will earn an average annual real rate of return of 3.53%, after all expenses over the same time period. The previous report, tabled in December 2022, assumed 3.69% for the base CPP account and 3.27% for the additional CPP account.
Historically, the Chief Actuary anticipated that the plan would need to draw on a small portion of investment earnings to supplement retirement payouts as early as 2021. However, due to stronger-than-projected employment metrics and higher active workforce payrolls, total annual contributions have consistently exceeded total benefit payouts. The current framework projects that the base CPP will not need to draw on portfolio returns to fund benefits until 2049.
source: cppib.com/en/our-performance>cpp-sustainability
Background: Who Invests The CPP Contributions?
Background: Who Invests The CPP Contributions?
The Canada Pension Plan Investment Board (CPPIB) was created in December 1997 by an Act of Parliament to manage the CPP investment portfolio. This federal Crown corporation operates like a private sector investment management company with several legislative safeguards to protect it from political interference.
Their role is "to invest the assets of the CPP Fund with a view to achieving a maximum rate of return without undue risk of loss".
The CPPIB does not set tax rates, administer pension benefits, or make government policy. Its sole purpose is to act as a professional asset management firm.
Once the CRA collects payroll deductions, any funds not immediately needed to pay out current retirees are handed over to the CPPIB. The CPPIB’s strict legislative mandate is to invest that pool of money in global markets (stocks, bonds, real estate, and infrastructure) to maximize returns without taking undue risks. They report their investment yields to the public and the government, providing the engine that grows the wealth of the fund.
Service Canada pays CPP benefits. The Chief Actuary of Canada reviews the funding of the CPP every three years. The last triennial report was released in December 2025. A special report followed in June 2026 because of Bill C-30. The next triennial report is expected in 2028.
source: www.cppinvestments.com/About_Us/
Canadian Payroll Tax Guide
Canadian Payroll Tax Guide | CRA Employment Status Tests
A Canadian payroll tax guide to walk you through your compliance responsibilities including the process for hiring an employee.
How To Pay Employees With Cash | Casual Employment
Learn how to pay employees with cash properly to protect your business while accommodating the employee. CRA has a strict definition of casual employment.
Is an Auto Allowance a Taxable Benefit? Tax Exempt?
When is an auto allowance a taxable benefit and when is it tax exempt? Are there other vehicle deduction limits I need to be aware of?
Author's note: S.A. Kenway directed the design of both infographics in this article, which were created with AI assistance.
Back to top